AI Is Moving into Your Financial Workflows. Is Your Business Ready for the Risk?
Where the risks begin
Financial data is among a company's most sensitive information. Connecting an AI assistant to accounting records, invoices, employee information, and other applications expands the number of places that data may be processed or exposed. An overly broad permission could allow the tool to retrieve information a particular workflow does not need. A mistaken reconciliation or fabricated explanation could distort a business decision. A compromised account or malicious content inside a document could also influence what an AI-enabled workflow sees or produces. And a vendor connection may introduce additional licensing, support, and data-handling obligations.
Privacy, compliance, and the cost of convenience
The risk is not limited to hackers. Businesses must understand where data is stored, who can see generated reports, how long records are retained, and whether third parties process the information. Healthcare providers, financial firms, and businesses holding customer or employee records may have contractual or regulatory duties that affect deployment. Microsoft says its Copilot enterprise protections respect existing user permissions and sensitivity labels, and that prompts and documents are not used to train underlying foundation models. Those protections are valuable, but they do not repair excessive permissions or eliminate the need for an internal review. Budget for licensing, integrations, training, validation, and the human time required to correct errors not just the advertised AI feature.
Five steps to adopt it responsibly
- Start with one low-risk workflow. Try summarizing an already-reviewed monthly report before allowing AI to draft journal entries.
- Review access first. Limit the assistant and connected applications to the minimum information required.
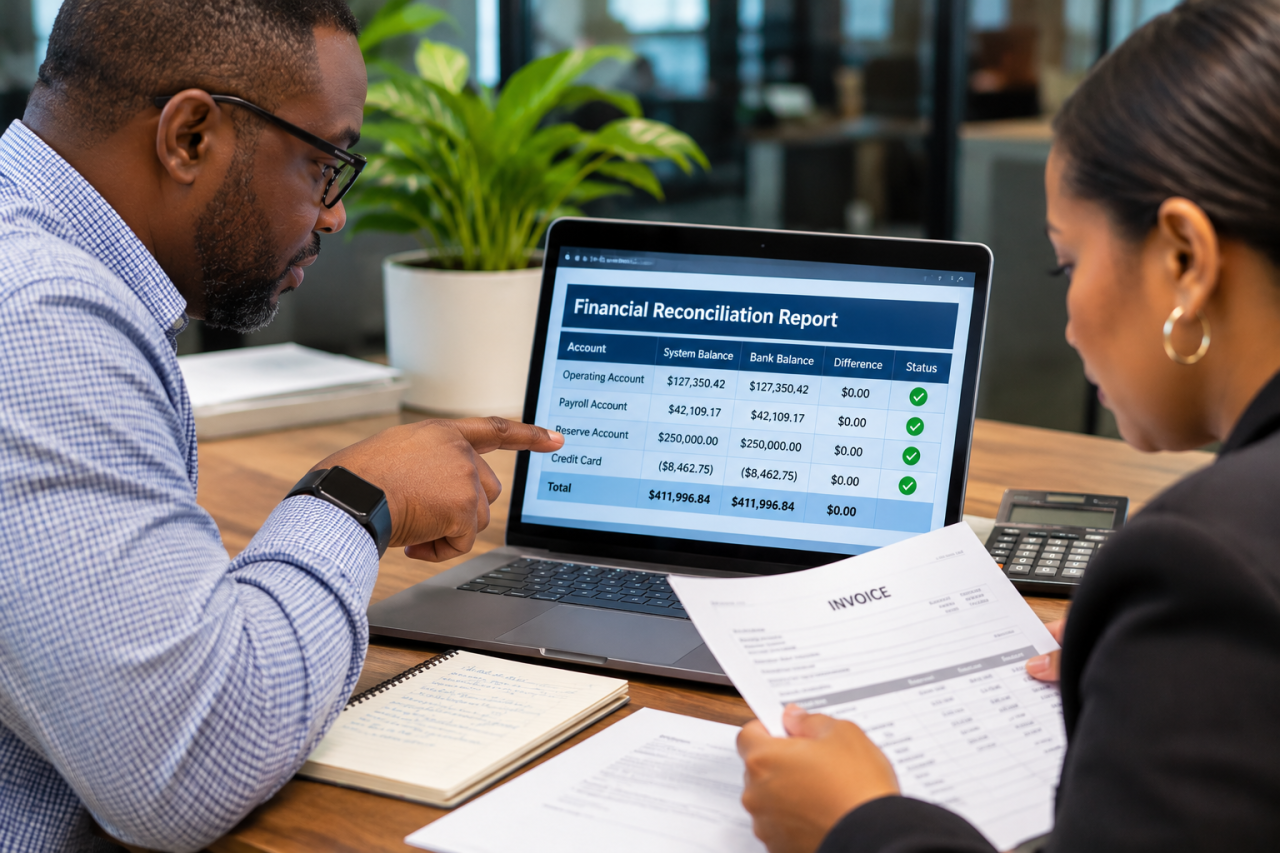
- Keep people in charge. Require a qualified employee to verify source records and approve financial entries, payments, or external disclosures.
- Test the exceptions. Check how the system handles missing transactions, duplicate invoices, unusual balances, and misleading document content.
- Measure real value. Compare time saved against corrections, subscriptions, integration work, and ongoing oversight.
The bigger lesson for small businesses
AI is becoming part of ordinary business software, not just a separate chatbot employee open when they need help writing something. That makes adoption easier, but it can also make new risks less visible. A feature embedded in a familiar application still deserves a business owner, an access review, and a plan for what happens when it gets something wrong. The right goal is not to automate every financial task. It is to improve accuracy and efficiency without surrendering accountability.
How LBT can help
At LBT Technology Group, LLC., we help independent, small, and midsize businesses look beyond whether a technology works to understand how it affects the organization's security, reliability, and business risk. Before you connect AI to financial or other sensitive workflows, make sure your permissions, monitoring, data protections, and approval processes are ready. Where others stop at cybersecurity, we go beyond to cybersecurity risk management.